

Cascais and Estoril: Luxury Market Trends for 2026
Updated: 29-10-2025 - Europe/Lisbon
Executive summary: In 2025 Portugal led the EU in year-on-year price growth (+17.2% in Q2, according to Eurostat), in a global context in which the “prime” has remained resilient and supply remains scarce in the areas in which it is located. prime. For 2026, we project annual valuation of 4-7% in the best micro-markets in Cascais and Estoril, gross yields of 4-6% in assets of excellence and additional prizes for projects branded/wellness with integrated services. Our team works only for buyers, with technical diligence and smooth negotiation.
1) Panorama 2025: Local, European and Global
Global (“prime” luxury): In H1 2025, 60% of the cities in the World Cities Index saw capital values grow; prime rents rose by ~2% and demand for HNWIs remained stable, supporting further appreciation in the 2nd half of the year. Savills, World Cities H1 2025. O Knight Frank Wealth Report 2025 confirms appetite for prime residential property and greater asset selectivity.
Europe: In Q2 2025 prices rose 5,1% in the euro area and 5,4% in the EU; Portugal stood out with the highest year-on-year increase. Eurostat, 03-10-2025. The outlook for southern European cities (including Lisbon) remained positive, with a shortage of supply sustaining prime prices. Savills Prime Price Forecasts.
Portugal: INE reports an acceleration in the price index in Q2 2025 and more transactions (+15.51Q3 year-on-year), a sign of robust demand. INE, Housing Price Index, 22-09-2025. At the same time, the perception of a gradual fall in rates improves confidence on the demand and credit side. Bank of Portugal, Bank Lending Survey.
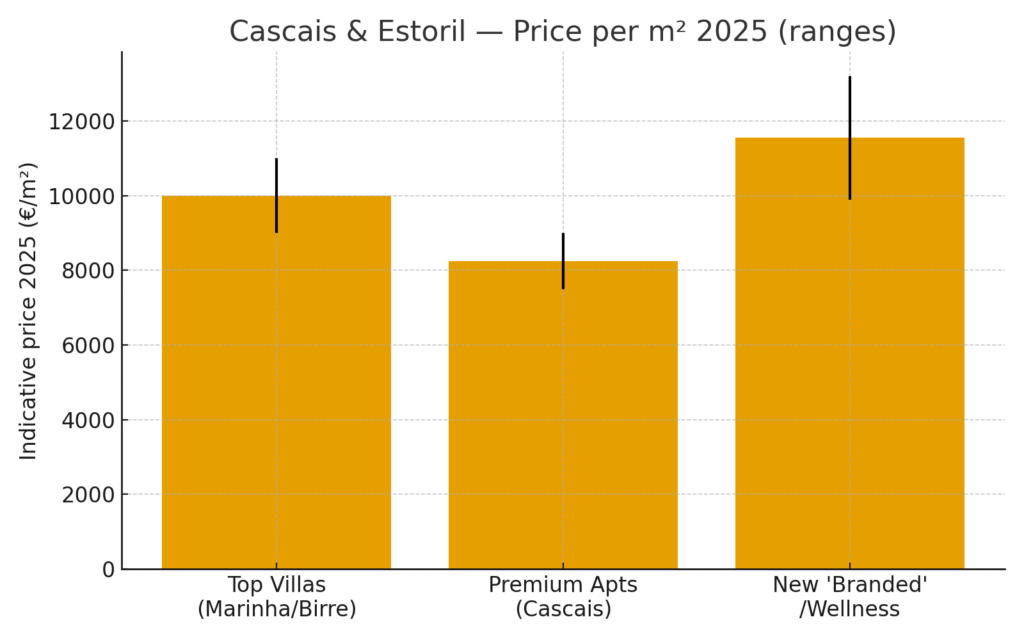
Cascais & Estoril: The zones prime (Quinta da Marinha, Birre, Cascais Centre, Monte Estoril) maintained a shortage of top product and stable international demand. Average asking prices in the municipality (all ranges) stood at ~€6,566/m² in September 2025, with the luxury segments well above this level. Idealista, Cascais and Estoril, 09-2025. The public outlook points to further rises in luxury in Cascais/Estoril and Lisbon, in the face of limited supply. Idealist, 24-06-2025.
2) Vectors that will shape 2026
2.1 Structurally scarce supply in prime areas
In Cascais/Estoril, assets with sea views, the right solar orientation and top communities have very low supply elasticity. With no significant pipeline of new ultra-luxury projects in A+ locations, price pressure remains.
2.2 HNWI demand and wealth migration
Quality of life, security, stable taxation in the core (moderate IMI vs. European comparables), international schools and proximity to Lisbon reinforce attractiveness. Global reports point to continued demand for prime real estate in southern European cities, with gradual rate cuts supporting confidence. Savills; Knight Frank.
2.3 Financing: interest is falling, but cash is still in charge
Gradual monetary normalisation in the euro area helps sentiment (see public statements by ECB decision-makers), but all-cash buyers continue to have a tactical advantage in negotiations. Reuters, 16-01-2025.
2.4 Concept and services: premium for “branded/wellness”
In the high-end segment, “location + concept + execution” increasingly covers the decision. Projects with services (concierge, wellness, club) and robust energy efficiency tend to negotiate at a premium over the comparable.
3) Forecasts for 2026: Price, Yields and Liquidity
Based on the combination of fundamentals (scarce supply, stable international demand, normalisation of rates and resilience of the prime in Europe), we project to 2026:
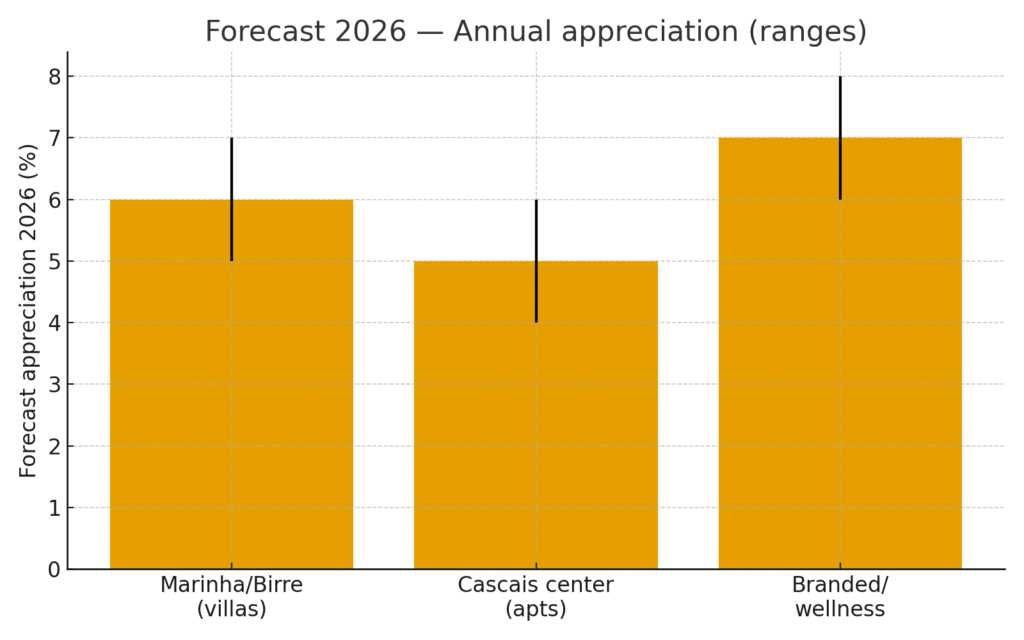
- Annual valuation aggregate of 4-7% in top micro-zones (Quinta da Marinha, Birre, Centro/Monte Estoril), dispersed by asset quality.
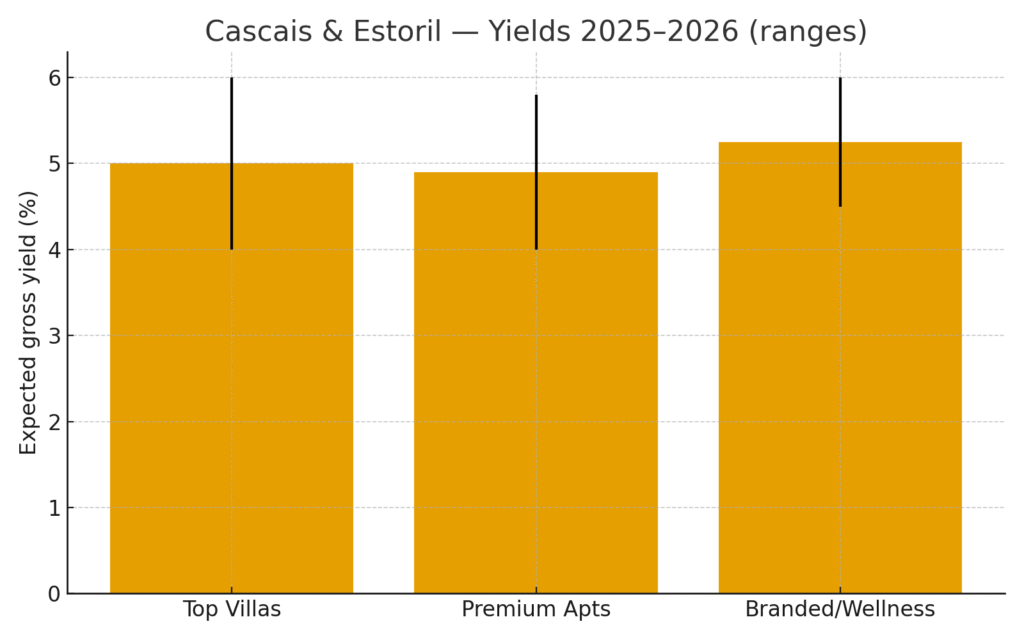
- Gross yields in 4-6% for prime assets (medium/long contracts), depending on micro-location, workmanship and management.
- Prize of 10-20% in “branded/wellness” compared to comparables without services.
Graphics (bilingual)
4) Risks and Attention Factors
- Public policy and taxation: surgical adjustments tend to exclude zones prime, In the case of the "luxury" segment, the impact is limited, but should be monitored. Executive Digest, 26-09-2025.
- Credit and evaluation: Unexpected interest rate rises or conservative valuations can extend terms; financing/valuation clauses in the CPCV are essential.
- Future offer: relevant pipeline of premium projects could squeeze premiums; for now, we don't see enough volume in the best micro-zones to turn the tables by 2026.
5) Practical implications for HNWI and Investors
- Define micro-zone and value thesis (view, light, walking distance, services). Time is a critical variable in future liquidity.
- Structure the all-in“ (IMT, Stamp Duty, legal, works) before you go ahead: see our guide Taxes & Costs.
- Technical and documentary due diligence: BOM + Register/Passbook + CPCV with conditions.
- Financing: integrate bank deadlines and valuation condition in the CPCV; see Financing for foreigners.
- Executionin selective markets, exclusive representation of the buyer reduces information asymmetries and the risk of “surprises”.
FAQ
What is the expected valuation in 2026 for the top of the range?
In the best micro-areas (Quinta da Marinha, Birre, Centro/Monte Estoril), we estimate +4-7%/year, assuming contained supply and stable international demand (European benchmarks: Eurostat; Savills).
Which yields are realistic in luxury?
4-6% raw, depending on location, product and rental management. In 2025, prime rents in several European cities outstripped the growth of capital values, signalling yield support. Savills, H1 2025.
Will taxes help?
The basic trajectory points to gradual normalisation in the euro area, which tends to support confidence. But cash buyers retain their negotiating advantage. Reuters.
Is this market still competitive compared to Spain?
Yes - product shortages prime, The safety and quality of life in Cascais/Estoril sustain local awards. In the Iberian Peninsula, the “prime” markets remain strong; see Spain's behaviour in 2024-25 as a regional benchmark. Cinco Días/El País.
Sources
- Eurostat - House prices up by 5.1% in the euro area (Q2 2025).
- INE - House Price Index, Q2 2025.
- Savills - World Cities Prime Residential Index, H1 2025 and Prime Residential Price Forecasts 2025.
- Knight Frank - The Wealth Report 2025.
- Bank of Portugal - Bank Lending Survey (Jan 2025).
- Idealist - Price/m² Cascais and Estoril (Sep 2025) and Luxury prices outlook.
- Executive Digest - Reduced VAT and exclusion from prime zones.
Next steps
If you're evaluating a €2-5M acquisition on the Line, talk to us. Independent Buyer's Agency, set up a conversation or download the Buyer's Guide. To go deeper:

 Português
 English (UK)